







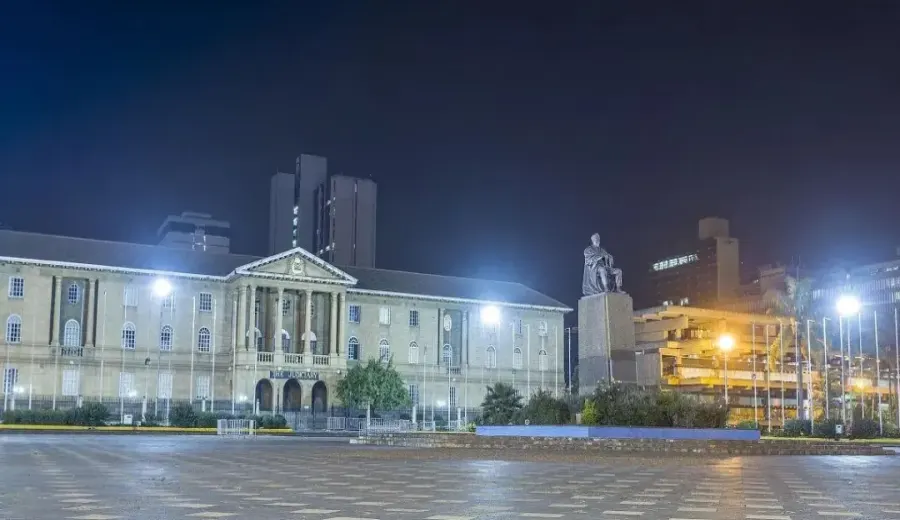
Introduction:Kenya’s Supreme Court ruled in August 2024 that the 2023 Finance Bill was constitutional, drawing nationwide attention. The new tax system increases duties on fuel and income, adding to the cost pressures faced by the coffee industry. Meanwhile, the EU’s Deforestation-Free Regulation (EUDR), which will be fully implemented starting January 2025, poses further export challenges for Kenyan coffee—of which only about 30% is currently certified. This article takes an in-depth look at the details of the tax reform, the current status of EUDR compliance, and explores coping strategies for smallholder farmers.
On August 20, Kenya’s Supreme Court issued a landmark ruling, overturning a previous decision by the Court of Appeal and ultimately declaring the 2023 Finance Act constitutional. This legislation had sparked large-scale demonstrations in cities such as the capital Nairobi, with opponents criticizing its provisions—including doubling the fuel value-added tax, introducing a new housing levy, and raising the top personal income tax rate—as exacerbating the burden on people’s livelihoods.
Notably, Kenya’s Court of Appeal had initially ruled the bill unconstitutional on the grounds of “insufficient public participation.” However, the Supreme Court clarified in its judgment that the legislative body had extensively gathered public input through diverse channels, thereby upholding the bill’s validity. The court has also scheduled hearings on September 10 and 11 to further clarify related disputes.
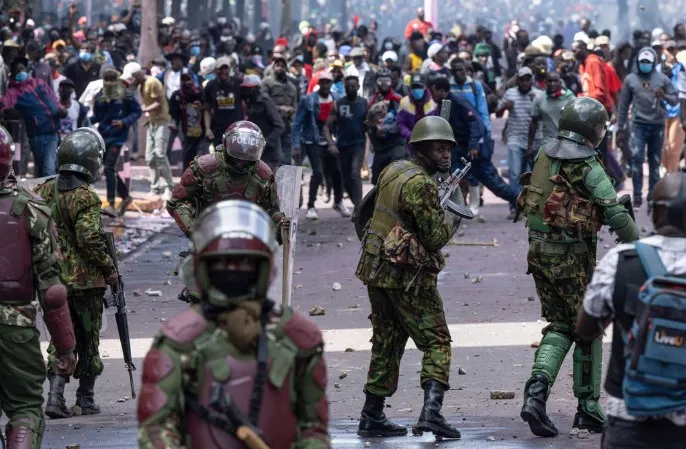
The backdrop to this ruling stems from the twists and turns in Kenya’s fiscal policy. The original version of the new Finance Bill, slated for implementation in 2024, was ultimately removed entirely from parliamentary proceedings—its 65 clauses deleted in full—following strong public backlash, including police-public clashes in the capital that resulted in injuries and fatalities. In the absence of an alternative plan, the government opted to retain the 2023 tax system and continue levying existing tax rates.
For the coffee industry, the tax adjustments have directly driven up production and transportation costs. While international coffee bean prices have risen due to fluctuations in output, the additional tax burden may force producers to raise end-market prices, further suppressing consumer demand. Industry insiders point out that the cost-pass-through effect will undermine the competitiveness of Kenyan coffee in the global market.
An even more severe challenge comes from the EU’s upcoming Deforestation-Free Regulation (EUDR), set to take effect in January 2025. This regulation requires imported goods to demonstrate that their production did not involve deforestation. Currently, only around 30% to 40% of Kenyan coffee meets relevant certification standards. Major certification bodies, such as the Rainforest Alliance, are actively assisting farmers with applications, but compliance progress in the remaining approximately 60% of producing regions is severely lagging.
Over 70% of Kenya’s coffee industry relies on the EU market, yet the majority of producers are smallholder farmers operating dispersedly. These producers not only have limited awareness of the specific requirements of the EUDR, but also face significant barriers due to the high compliance costs. Industry analysis shows that each step—from forest traceability, documentation, to third-party verification—requires resource investment, placing heavy pressure on smallholders with limited individual yields.
Experts recommend that the Kenyan government accelerate the rollout of certification support programs, lowering the entry barrier for smallholders by simplifying procedures and offering subsidies. At the same time, regional cooperatives can play a crucial role by pooling resources to handle certifications collectively, improving overall compliance efficiency. Failure to respond promptly could not only result in export disruptions but also exacerbate price volatility in the international market.
The above content is compiled by CoffeeHunters, a coffee news website.


