Introduction:Since 2022, the pricing trends of coffee and new-style tea beverages have moved in opposite directions. Coffee brands have successively raised their prices, while new tea drinks have proactively lowered prices to compete for market share. This polarization in consumer spending reflects fluctuations in raw material costs, differences in brand strategies, and shifts in consumer preferences. This article delves into the reasons behind the divergence in tea and coffee pricing and provides practical market insights to help readers grasp the emerging trends in beverage consumption.
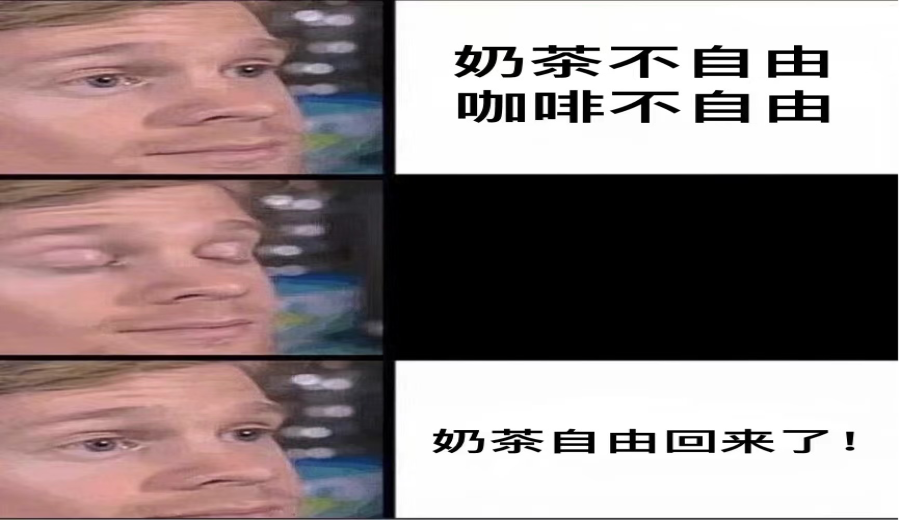
Entering 2022, many office workers noticed that their once taken-for-granted “bubble tea freedom” and “coffee freedom” were quietly slipping away. At the start of the year, new-style tea brands began adjusting their strategies, with bubble tea price hikes leaving many exclaiming that it had become unaffordable. Soon after, coffee brands such as Starbucks and Luckin also raised their prices due to rising raw material costs. However, the situation quickly reversed—some tea brands like Heytea and Nayuki proactively cut prices, even introducing drinks as low as 9 RMB to lure consumers back. Meanwhile, the coffee market continued to climb, with little sign of price relief. Behind this one-down-one-up dynamic lies deeper structural changes: a more rational consumer market, the fading traffic dividend of tea beverages, and the coffee industry still in an expansion phase.
Looking back to early 2022, many consumers, under the pressure of rising living costs, first faced higher bubble tea prices, followed by coffee joining the upward trend. In contrast, tea brands like Heytea and Nayuki swiftly adjusted their strategies, launching a series of affordable products, with some drink prices even dropping to 9 RMB, successfully attracting budget-conscious consumers. Meanwhile, Cha Yan Yue Se, which had long adhered to a premium positioning, had only increased its prices by 1 RMB over five and a half years, making it increasingly less appealing. In fact, since the rise of the first premium new-style tea brand, the market has undergone seven years of transformation. Consumers have shifted from initial novelty to rational consumption, especially after the pandemic, when concerns over health and economic stability further influenced purchasing decisions.
According to the 2020–2021 Chinese New Tea Beverage Industry Development Report, over half (57%) of consumers prefer bubble tea priced between 10 and 15 RMB, with only 27% willing to accept prices between 15 and 20 RMB. An increasing number of white-collar workers are reducing their purchase frequency due to high bubble tea prices and health concerns. Consumers are gradually awakening from blindly chasing brands and trends, with growing skepticism toward excessive pricing, and the traffic dividend of new-style tea beverages is gradually waning. To maintain market share and expand into lower-tier markets, Heytea and Nayuki have announced price reduction strategies, not only introducing lower-priced drinks but also committing to capping future new product prices at 20 RMB. Heytea has explicitly stated that it will no longer launch products priced above 29 RMB.
Mixue Ice Cream & Tea, which has been deeply rooted in lower-tier markets for years, with most of its products priced below 10 RMB, achieved a revenue of 6.5 billion RMB and a net profit of 800 million RMB as early as 2019, demonstrating strong profitability through a low-margin, high-volume model. The low-price strategy not only failed to weaken its market competitiveness but instead became a key factor in expanding its market share.
In contrast, the coffee market presents a very different picture.Affected by rising international coffee futures prices and increased operational costs, multiple brands including Starbucks, Luckin, and Tims have successively adjusted their prices. Particularly in mid-February, Starbucks took the lead in initiating a price hike mechanism, drawing market attention, followed by other brands making similar adjustments.
Compared to new-style tea beverages, which have greater flexibility in ingredient selection, coffee relies on a relatively uniform set of ingredients, with its cost structure closely tied to international coffee bean market trends.Coffee is a commodity not only influenced by market supply and demand but also significantly different from tea in terms of storage and shelf life. When raw material prices fluctuate, coffee brands often have no choice but to raise prices in order to maintain operational quality and service standards. Heytea has stated that due to accumulated supply chain experience, it can offer price reductions while ensuring product quality; however, the limitations on coffee ingredients leave less room for flexible pricing.
From a market trend perspective, new-style tea beverages are moving toward more affordable pricing and market segmentation. The 2021 New Tea Beverage Research Report released by the China Chain Store & Franchise Association points out that over the next 2 to 3 years, the growth rate of the new tea beverage market will gradually slow to 10%–15%. Although new brands continue to emerge, the barriers to entry for newcomers have clearly risen. In contrast, the coffee market is still in the early stages of expansion, with huge potential. According to Frost & Sullivan data, it is projected that by 2023, China’s per capita annual consumption of freshly brewed coffee will rise from 1.8 cups in 2020 to 5.5 cups, with the overall market size expected to grow from 63.3 billion RMB to 157.9 billion RMB.
In terms of brand competition, Starbucks’ dominance has been challenged. Luckin, with its mainstream pricing of 10 to 20 RMB, has not only successfully overtaken its rivals but also become the coffee brand with the largest number of chain stores in China. Meanwhile, international brands such as Tims, Blue Bottle, and Stumptown are actively expanding in the Chinese market, vying for market share. Tims China has even set a goal to open 2,750 stores by 2026. While the gap between tea beverage brands is narrowing and price cuts have become a common tactic for competition and marketing, the coffee market in its expansion phase sees price increases not only reflecting cost pressures but also serving as an important strategy for brand positioning and market differentiation.
The above content is compiled by CoffeeHunters, a coffee news website.