Introduction:Luckin Coffee’s 2021 financial report shows that its total annual net revenue approached 8 billion RMB, with the number of stores surpassing that of Starbucks China. This article delves into how Luckin has gradually reached a profitability inflection point through a dual strategy of company-operated and franchised stores, market expansion in lower-tier cities, and optimized delivery costs, while also exploring its future market layout and challenges.
Luckin Coffee demonstrated strong growth momentum in the 2021 fiscal year, achieving a total annual net revenue of 7.965 billion RMB, a significant increase of 97.5% compared to the previous year; in the fourth quarter alone, revenue was 2.4327 billion RMB, up 80.7% year-on-year. This performance not only reflects the brand’s strong recovery but also highlights the success of its market expansion strategy.
By the end of 2021, Luckin had a total of 6,024 stores in China, successfully surpassing Starbucks’ store count in the Chinese market. This includes 4,397 company-operated stores and 1,627 licensed (franchised) stores. Compared to 2020, the total net increase in stores for the year was 1,221, a growth rate of 25.4%, with licensed stores accounting for as much as 60%, showing that non-company-operated models have become an important driver of brand expansion.
Breaking down the revenue sources, Luckin’s company-operated stores contributed 6.193 billion RMB in revenue in 2021, a year-on-year increase of 78.3%; in the fourth quarter alone, company-operated store revenue reached 1.837 billion RMB, with an annual growth rate of 61%. In contrast, the performance of licensed stores was even more eye-catching, with annual revenue reaching 1.306 billion RMB, a surge of 312.5% year-on-year. These licensed stores are mostly concentrated in third-, fourth-, and fifth-tier cities, and even extend to some rural areas, not only expanding the brand’s coverage but also significantly boosting overall revenue. It is estimated that the average annual revenue per licensed store is about 800,000 RMB.
Notably, in this financial report, Luckin for the first time separately listed the fourth-quarter delivery expenses, amounting to 233 million RMB, a year-on-year increase of 83.8%. The official explanation is that this was mainly due to a significant increase in the number of delivery orders. As coffee consumption habits gradually penetrate from first- and second-tier major cities to third- and fourth-tier counties, and even some remote villages and towns, the coffee market is welcoming a new wave of growth opportunities. At the same time, the trend of consumption upgrading in first- and second-tier cities, coupled with the narrowing urban-rural consumption gap, has also accelerated the overall market expansion.
Luckin’s financial performance also reveals a clear trend toward turning losses into profits. In the fourth quarter of 2020, the Non-GAAP (non-U.S. generally accepted accounting principles) operating loss was 369 million RMB, but by the same period in 2021, this figure had narrowed significantly to 23.6 million RMB, just one step away from achieving profitability. This shows that the company has made significant progress in cost control, operational efficiency, and market strategy.
In addition, Luckin mentioned in the report that with the completion of the provisional liquidation process in the first quarter of 2022, the company expects that expenses and losses related to past fraudulent transactions and restructuring will significantly decrease in the second quarter of 2022. This means the corporate governance structure has gradually stabilized, laying a solid foundation for future financial transparency and operational stability.
Once plunged into a low point due to the financial fraud scandal, Luckin is now completely free from the control of the previous management and is gradually returning to the path of growth. The outside world is widely watching whether it will return to the Nasdaq main board. Although Luckin denied related rumors in late January 2022, the market remains full of anticipation for its future moves.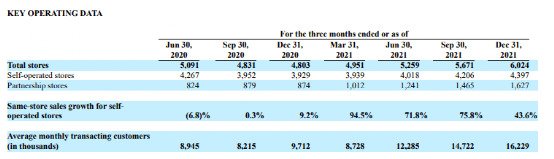
It is worth mentioning that although Luckin is currently on the over-the-counter (OTC) pink sheet market, it still insists on regularly publishing financial reports, demonstrating its emphasis on information transparency and investor confidence. From surpassing Starbucks in store count to the gradually clear profitability inflection point, Luckin’s next steps in layout are worth continued attention.
The above content is compiled by CoffeeHunters, a coffee news website.