Introduction:In recent years, Luckin Coffee has frequently opened stores near or even directly opposite Starbucks, sparking widespread market discussion. Behind this “head-to-head competition” strategy lies not only precise calculations of commercial district foot traffic but also reflects the rising consumer demand for high-value, affordable coffee. This article delves into how Luckin leverages the halo effect of Starbucks to attract customers, explores how the differences in pricing and positioning between the two major brands influence consumer choices, and examines the long-term impact of this competition on China’s domestic coffee market.
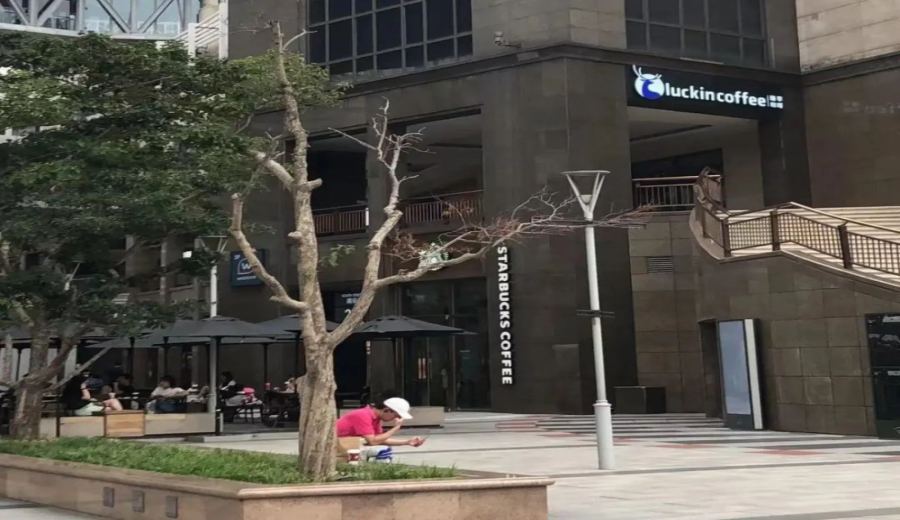
Walking through the commercial districts of China’s first- and second-tier cities, it’s not hard to notice the increasingly nuanced relationship in store locations between Luckin Coffee and Starbucks—some outlets are just a wall apart, some face each other across the street, and some are even located on different floors of the same building. This “adjacent layout” is no longer accidental but a carefully planned strategy by Luckin. Observations show that in recent years, Luckin has deliberately chosen to open new stores near or even directly opposite Starbucks, aiming to capture Starbucks’ steady stream of foot traffic while standing out with its own advantages.
As the first foreign coffee brand to enter China, Starbucks has built up strong brand recognition and commercial district appeal over the past two decades. Its site selection is usually rigorously evaluated, often located in busy commercial areas or office hubs that naturally attract large crowds. Luckin’s choice to set up shop nearby is precisely based on this, hoping to capitalize on the popularity brought by Starbucks while distinguishing itself with a more approachable image.
The success of this strategy is inseparable from subtle shifts in consumer psychology. With the concept of affordable coffee becoming more mainstream, many customers have formed a price anchor of “a cup of coffee costing around 20–30 yuan.” In comparison, Starbucks’ average price of over 30 yuan is easily seen as “a bit expensive.” Especially for price-sensitive younger demographics, the diverse flavors and cost-effectiveness offered by Luckin are more appealing. Additionally, the rise of domestic brands has fostered a consumer sentiment that makes Luckin more likely to gain recognition from local consumers when compared to the foreign brand Starbucks.
The positioning differences between the two brands further intensify this competitive dynamic. Starbucks emphasizes the concept of the “third space,” highlighting a comfortable environment and social experience, with store designs typically more spacious, suitable for business meetings or leisure relaxation. However, this also means higher operating costs, which are reflected in its pricing. In contrast, Luckin focuses on the “fast-consumption coffee” market, with convenience and efficiency at its core. Its stores are smaller in size, with faster service, making it more suitable for office workers to quickly purchase takeout. It also offers a wider range of flavors, including currently popular specialty drinks.
From the consumer response perspective, this “adjacent competition” has indeed created an interesting contrast effect. Many customers will specifically visit both stores to compare prices and products, and may even change their original choice due to price differences or promotional activities. Luckin’s frequent discount coupons and membership benefits further reduce the actual purchase cost, while Starbucks, although also offering digital discounts, generally provides less substantial markdowns. This difference gives Luckin an advantage in the price-sensitive market segment.
However, can Luckin’s strategy of opening stores right next to Starbucks really shake Starbucks’ market position? According to Starbucks’ latest financial report, although its net revenue in the Chinese market has grown, the rate of increase has significantly slowed, partly due to its inability to fully attract the new generation of consumers, along with some loyal customers shifting to other brands. Notably, several emerging domestic coffee brands in recent years share similarities with Luckin in terms of product positioning, pricing strategy, or target customer groups, posing an even greater challenge to Starbucks.
Industry analysts point out that Luckin’s success lies in addressing two major pain points in the coffee market: the high experience threshold and lack of portability. Traditional cafés, with their high prices and slow pace, often deter many consumers, whereas Luckin, with its takeout-focused, affordably priced model, lowers the barrier to entry, transforming coffee from a luxury indulgence into a daily beverage. At the same time, its rich variety of flavors—from classic Americano and latte to innovative specialty drinks—caters to the taste preferences of different consumers.
As for whether Luckin can “steal” Starbucks’ customers, the answer is not absolute. Consumers visit coffee shops for various reasons: some seek environment and experience, others prioritize convenience and value. Different brands each have their unique appeals. Starbucks still retains a loyal customer base, especially those who value the ambiance of the space, while Luckin, with its flexible strategy and high cost-performance ratio, continues to expand its market share. This competition may ultimately drive both parties to continuously optimize their services and products, offering consumers even more choices.
The above content is compiled by CoffeeHunters, a coffee news website.