Introduction:As an important category in the coffee market, ready-to-drink (RTD) coffee accounts for only about 10% of the market share but is rapidly approaching the 10-billion-yuan mark with high growth momentum. Under the pressure of price competition in freshly ground coffee, how can RTD coffee maintain its position through convenience and cost-effectiveness? This article delves into the development trajectory, market landscape, consumer trends, and future challenges of RTD coffee, helping readers fully grasp this rapidly emerging sector.
China’s coffee market continues to expand, with instant coffee, freshly ground coffee, and RTD coffee each occupying their own territory, forming a diversified development pattern. Among them, although RTD coffee currently makes up only about 10% of the overall market—seemingly low-profile—its growth rate far exceeds the market average, particularly surpassing that of traditional soft drinks and bottled water. The overall market size has already approached the 10-billion-yuan threshold.
Looking back at the development history of RTD coffee in China, as early as 1998, international brands such as Suntory were the first to introduce canned and bottled coffee to the market. Through retail channels like supermarkets and coffee shops, they gradually cultivated the first wave of consumers. Subsequently, more domestic and international brands joined the fray, including Nestlé, Starbucks, COSTA, Uni-President, Yili, Nongfu Spring, Coca-Cola, Tims, and others, making competition in this niche market increasingly fierce.
According to market observations, Nestlé, with its first-mover advantage from entering the market early, still holds the top spot in market share. Starbucks follows closely, ranking second. Overall, although RTD coffee is not as widely consumed as instant coffee (which accounts for about 70% or more), nor as highly regarded as freshly ground coffee (about 20%), its status within overall coffee consumption is steadily rising.
Historical data shows that in 2018, RTD coffee accounted for only 10.1% of coffee consumption in China, compared to 71.8% for instant and 18.1% for freshly ground. Although it remains a niche, as consumer demand diversifies and product differentiation advances, the market acceptance of RTD coffee is gradually increasing, and its potential should not be overlooked.
The rapid growth of RTD coffee is primarily driven by dual forces from the consumer and industry sides. According to statistics from Headland Research Institute, from 2017 to 2021, China’s RTD coffee market expanded at a compound annual growth rate of 19.3%. In just a few years, the market size doubled to 9.64 billion yuan, and future growth potential remains broad. Notably, its growth rate significantly outpaces that of soft drinks and general bottled water.
For consumers, the popularity of RTD coffee mainly stems from its consistent taste, no need for brewing, availability anytime and anywhere, and ability to provide a quick energy boost—characteristics that fit well with the pace of modern busy life. Additionally, high cost-effectiveness is another key reason many consumers choose RTD coffee. Especially when compared to freshly ground coffee, RTD coffee often comes in larger servings at lower prices, becoming a daily alternative for some coffee enthusiasts.
As public expectations for coffee quality continue to rise, RTD coffee is also gradually moving toward premiumization and high-end development. According to the “2020 Ready-to-Drink Coffee Innovation Trends Report,” as many as 45% of consumers prefer RTD coffee made with high-quality milk sources, while another 44% hope for the use of premium coffee beans. This trend indicates that premiumization will become one of the mainstream directions for the future RTD coffee market.
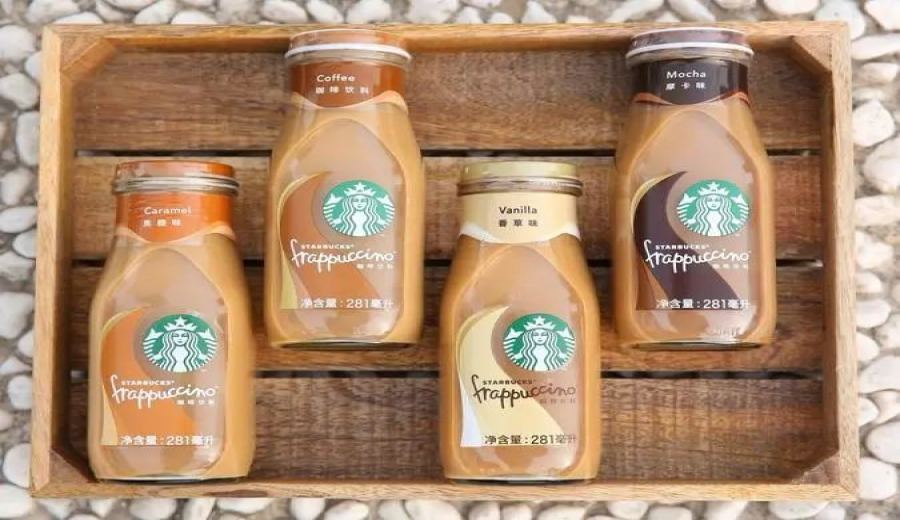
However, the shift toward premiumization and high-end also comes with a price increase. Products that previously sold for around 5 yuan have, after upgrading ingredients and processing, commonly seen prices rise to the 10 to 16 yuan range. For example, Starbucks’ Frappuccino coffee, in a 281 ml size, is priced at about 16 yuan—close to the price range of a regular cup of freshly ground coffee. At such price points, whether consumers will continue to make repeat purchases will be a major challenge for the development of RTD coffee.
Therefore, how to set reasonable pricing strategies while improving quality will be a critical issue that RTD coffee brands must carefully consider, and it is also key to maintaining market competitiveness and consumer loyalty.
The ability of RTD coffee to rise as a high-growth beverage category is inseparable from the active involvement of domestic and international brand giants. As more brands join the market, although competition intensifies, it also drives continuous improvement in overall product quality and innovation capabilities. It is expected that in the future, RTD coffee will develop toward higher-end, more premium, and more diverse formats to meet consumers’ increasingly refined and personalized needs.
The above content is compiled by CoffeeHunters, a coffee news website.