








Introduction:As the world’s largest producer of Robusta coffee, Vietnam faced challenges of declining production and tight inventory in the 2023/24 season. This article provides an in-depth analysis of harvest conditions in key growing regions, changes in cultivation structure, and shifts in international market demand, helping readers grasp the key factors influencing Robusta bean price trends and supply dynamics — offering practical insights for purchasing or brewing decisions.
The Vietnam Coffee - Cocoa Association signaled important developments at the 27th Asian International Conference: due to the triple impact of reduced output, nearly depleted stocks, and rising domestic demand, Vietnam’s overall coffee exports in the 2023/24 season are very likely to be lower than last year, with export prices expected to remain at high levels.
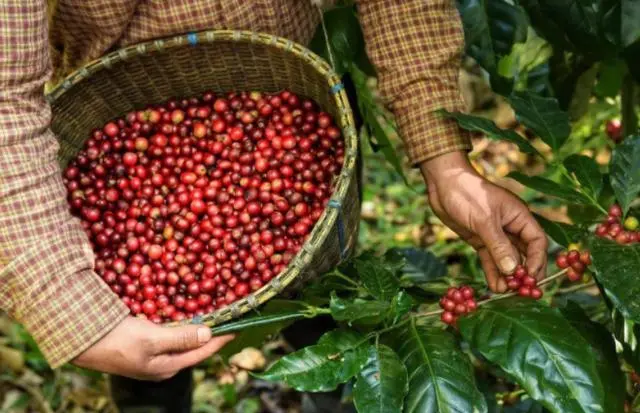
As a major global supplier of Robusta coffee, Vietnam is currently in the harvest phase of the 2023/24 season. However, according to the association’s chairman, who spoke at a conference held in Ho Chi Minh City on December 5–6, the overall harvest progress is only about halfway complete, and the estimated output is projected to be even lower than previously forecast. Hit by poor weather and shrinking planted area, the new season’s output may only reach between 1.6 million and 1.7 million tonnes, a significant drop from the previous season’s 1.78 million tonnes.
Not only has production decreased, but export performance has also contracted. From January to November 2023, Vietnam’s coffee exports have already fallen by nearly 13% compared to the same period in 2022, with the full-year decline potentially widening to 15%.
Local Vietnamese exporter Intimex Group pointed out that in the central and southern key coffee-growing regions, planted areas are gradually shrinking. The main reason is that coffee yields only about 200 million Vietnamese dong per hectare, while switching to avocado cultivation can generate up to 1,115 billion Vietnamese dong per hectare — more than five times the income from coffee — leading many farmers to shift to the more profitable avocado crop. Data from the Ministry of Agriculture and Rural Development also shows that the officially recorded coffee planting area is about 700,000 hectares, but the actual figure may be just over 600,000 hectares.
On the global market front, coffee supply has shown a clear shortage over the past two years, with inventory levels dropping and prices significantly impacted. In 2023, global consumption of Robusta beans grew by 10%, while Arabica production declined by 8%, further exacerbating the supply-demand imbalance and driving up Robusta bean market prices.
Notably, in the early stages of the 2023/24 season, coffee bean prices in the Vietnamese market soared to 60,000 Vietnamese dong per kilogram — a historically unprecedented high in the country’s coffee-growing regions.
The industry generally expects that before Indonesia and Brazil enter their new production seasons in April–May 2024, demand for Vietnamese Robusta coffee in the European market will remain strong. However, due to Vietnam’s sharp production decline, insufficient inventory, and rising domestic consumer demand, Vietnam’s coffee exports in the 2023/24 season may only reach 1.4 million tonnes, lower than the performance in the 2022/23 season.
Before the new harvest seasons in Indonesia and Brazil begin, Robusta coffee bean prices are expected to continue trending upward, with this high-price phase lasting at least until April 2024. For traders, roasters, and consumers closely monitoring coffee bean market dynamics, understanding these key variables will help prepare for price fluctuations and supply changes in advance.
The above content is compiled by CoffeeHunters, a coffee news website.


