Introduction:In recent years, China's coffee market has undergone significant changes in both scale and consumer habits, shifting from an instant coffee–dominated market to the rise of freshly ground coffee, and expanding from first-tier cities to lower-tier markets. This article will analyze the 2023 market size forecast, key annual growth rate data, and how chain expansion, the rise of online channels, and youth consumption behavior are propelling the industry into a period of rapid growth—helping readers grasp the transformation direction of the coffee industry over the next five years.
Over the past two decades, the positioning of coffee in the Chinese market has shifted from a novel imported product to a daily beverage for many. Market research data shows that between 2013 and 2018, China's coffee industry achieved a compound annual growth rate (CAGR) as high as 29.54%, with a year-on-year increase of 31% recorded in 2021. Looking ahead to 2022–2025, the market is expected to continue expanding at a CAGR of 9.63%, with the 2023 market size projected to reach RMB 180 billion, and potentially surpassing the RMB 1 trillion mark by 2025.
Behind this wave of growth are multiple driving forces, including chain brands actively expanding into third-tier and lower-tier cities, the rise of live-streaming and mini-program shopping, and the increasing acceptance of coffee drinking among younger demographics. At the same time, the market share of freshly ground coffee is expected to climb to over 51%, while instant coffee gradually contracts to below 40%, indicating a shift in consumer taste toward higher quality and more refined options—signaling that the overall industry is entering a phase of consumption upgrade and high growth.
Chain brands accelerate expansion into lower-tier markets
With the acceleration of work and life rhythms after the pandemic, the demand for coffee as a pick-me-up has risen significantly, coupled with the gradual popularization of specialty coffee culture. The market predicts that in 2023, the proportion of freshly ground coffee in China will surpass that of instant coffee, reaching over 51%. Freshly ground coffee is seen as an important indicator of consumption upgrade, and its growth potential has garnered high attention from the industry. Compared to the global CAGR of 5.7% for freshly ground coffee consumption, China’s 24.6% highlights enormous development potential, providing chain brands with an excellent opportunity to overtake on the curve.
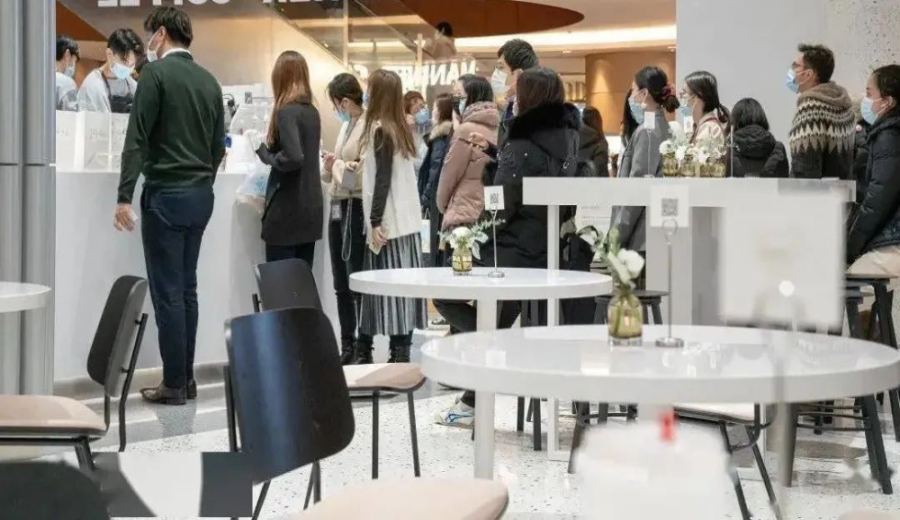
In recent years, many workers originally concentrated in first-tier cities have returned to third-, fourth-, and fifth-tier towns, also driving local demand for coffee. To capture these emerging markets, major chain brands have accelerated their store expansion. According to market statistics, the brands leading in new store openings in 2022 included Luckin Coffee (2,939 new stores), Luckin (1,521 new stores), and McDonald’s Coffee (763 new stores). As of the statistical cutoff, the brands with the most operating stores nationwide were, in order, Luckin Coffee (8,171 stores), Starbucks (6,882 stores), and McDonald’s Coffee (2,530 stores).
Mini-programs and live-streaming drive online consumption boom
The rapid development of live-streaming and e-commerce in China has injected new vitality into coffee sales. More and more consumers are using live-streaming platforms to explore coffee equipment, learn about the flavor profiles and brewing techniques of various coffee beans, and gradually develop the habit of placing orders online for convenience and discounts. Through live interaction, not only is consumers' understanding of coffee enhanced, but coffee is also further integrated into home brewing scenarios beyond being just a beverage.
At the retail end, mini-programs have become an important sales channel beyond physical stores and e-commerce platforms. The main consumer demographic is concentrated between the ages of 23 and 40—people who value shopping efficiency and convenience, and have a high demand for mobile applications. Mini-programs integrate social media and e-commerce functions, allowing consumers to pre-order products, reduce wait times, and enabling merchants to more flexibly adjust inventory and supply, thereby further lowering operational costs and offering more competitive pricing for products.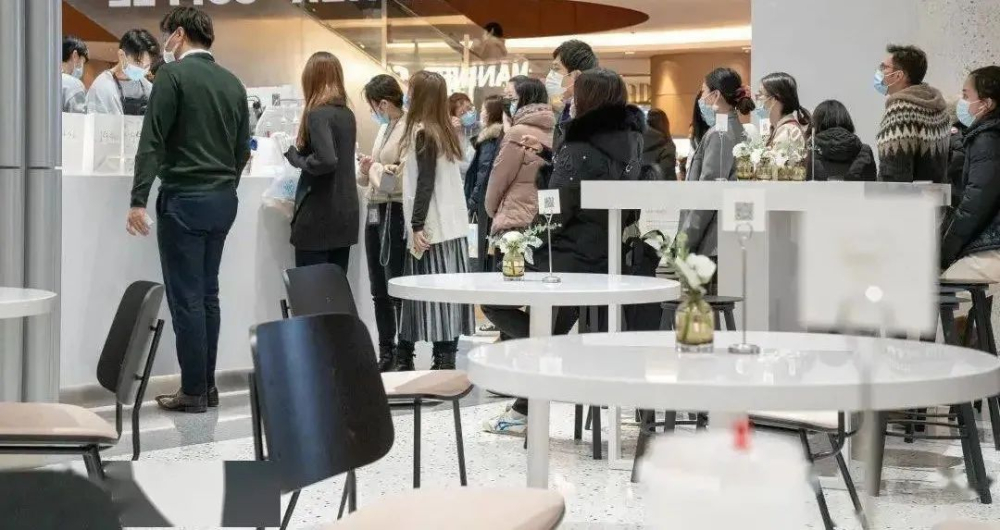
Younger demographics develop coffee drinking habits
The combined forces of chain brand expansion, live-streaming sales, and mini-program retail have jointly accelerated the formation of coffee drinking habits among younger consumers. Compared to countries with mature coffee cultures, the Chinese market is still in its early stages of development, with huge potential. Data shows that the three main reasons Chinese consumers drink coffee are: to stay alert (53.1%), fondness for coffee flavors (53.2%), and enjoyment of café ambiance and service (31.3%). Most consumers spend between RMB 10 and RMB 40 per café visit, with RMB 15 to RMB 25 being the most common range.
Currently, coffee consumers in the Chinese market generally place importance on product quality, with most single purchases falling within the mid-price range, reflecting a focus on cost-performance. The standardized products offered by chain brands, the flavor introductions provided by live-stream shopping guides, and the convenience services of mini-programs are key factors meeting these demands. Observing market trends, coffee consumption in the coming years will focus more on the needs of Millennials (Generation Z) and Gen Z (under 40), enhancing the social attributes of coffee, launching more portable and ready-to-drink products, while also increasing the supply of high-quality imported coffee beans to meet consumers’ pursuit of diverse flavors.
The above content is compiled by CoffeeHunters, a coffee news website.