Introduction:Prominent chain coffee brands such as Starbucks, Luckin, and Tims have successively adjusted their prices, sparking market discussions. It is generally believed that this is due to a sharp decline in Brazilian coffee bean production and tight inventory, but is that really the case? This article delves into the truth behind the price hikes of chain coffee shops, dissecting key factors such as climate impacts in producing regions, transportation bottlenecks, and global inflationary pressures, while also providing an overview of the current state of the coffee market and what consumers should pay attention to.
Recently, multiple chain coffee brands including Starbucks, Luckin, and Tims Hortons have announced product price increases, drawing considerable attention and discussion from consumers. Most market opinions attribute this wave of price hikes to poor Brazilian coffee bean harvests, leading to a decline in ICE exchange Arabica coffee bean inventories and soaring prices. However, the head of Brazil’s official export agency offered a different perspective, stating that although inventories have decreased, they remain at a reasonable level, and the real challenges lie in multiple pressures such as transportation and global inflation.
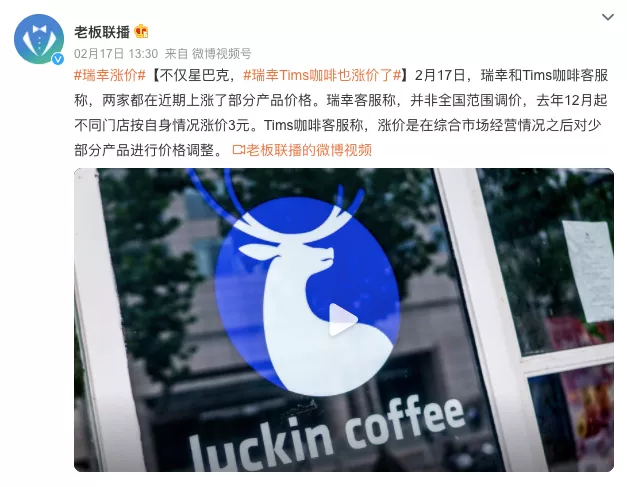
As early as February 2, this year, Starbucks CEO Kevin Johnson revealed that multiple rounds of price adjustments would be carried out in the coming months. Although Starbucks pricing in the Chinese market has always been relatively high—nearly double that of the U.S. market—at the time, it was expected that the Chinese market might be excluded from the price adjustment list. Surprisingly, even with already premium pricing in China, Starbucks still chose to raise prices, which caught many consumers off guard.
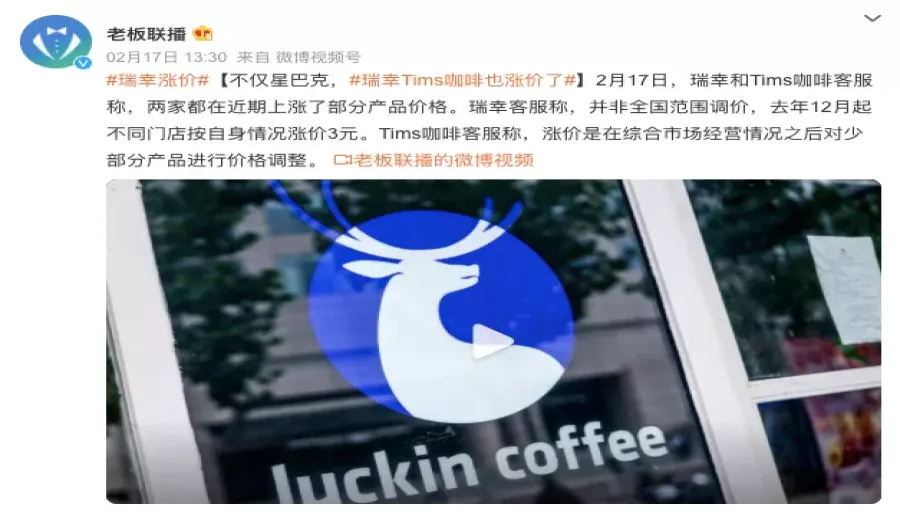
Coincidentally, shortly after Starbucks announced its price adjustment, Luckin and Tims Hortons, which had quietly raised prices earlier, also became the focus of discussion. Many observers believe that this wave of price hikes mainly stems from reduced Brazilian coffee bean production, particularly the severe climate challenges faced during the 2021 harvest season, which led to a rapid decline in ICE Arabica coffee bean inventories and further pushed up procurement costs. However, according to Nicolas Rueda, head of Brazil’s coffee export management agency Cecafe, Brazilian coffee bean inventories have not actually been exhausted. Despite the overall reduction, they are still sufficient to meet market demand.
Nicolas Rueda further explained that the 2021 Brazilian Arabica coffee bean production was severely impacted, mainly due to extreme weather conditions such as frost and drought that year, resulting in a total output that was 25% lower than in 2020, at only about 47 million bags (each bag weighing 60 kilograms). In addition, reduced transportation efficiency during the pandemic also affected the liquidity of ICE inventories. However, he pointed out that the 2020 harvest was quite bountiful, and the current global issue of container shortages means that many inventories remain stranded in ports or warehouses, with the actual amount of coffee beans available for trade not as tight as the market imagines. Therefore, soaring prices and tight inventories are not entirely equivalent—transportation and inflation are the real driving forces behind the scenes.
In fact, in addition to the soaring freight costs caused by container shortages, which affect the global supply efficiency of coffee beans, chain coffee brands face greater pressure from the overall inflationary environment, including across-the-board increases in labor costs, rental expenses, and raw material prices. Over the more than two years since the outbreak of the pandemic, the beverage industry has also been severely impacted, especially chain brands that must bear fixed and variable costs such as multi-store rents, employee salaries, supply chain management, and staff training. In an uncertain market outlook, gradually adjusting prices has become a common risk management measure.
It is worth noting that the price adjustments by Luckin and Tims occurred in early December last year and early January this year, respectively, both of which were ahead of the time when Arabica coffee bean prices “surged” to nearly a decade-high. This shows that the pricing actions of these two brands were more strategic adjustments based on their own operational conditions, rather than a simple reaction to a surge in raw material costs.
As for Starbucks, although the price adjustment this time seems modest—with only a CNY 1 to 2 increase in the Chinese market—it has been nearly four years since the last adjustment, and the announcement at this time has still sparked considerable discussion. Some observers noted that although the increase is small, announcing a price hike at a sensitive moment in the market inevitably leaves a strong impression on consumers. However, from an operational perspective, with simultaneous increases in bean prices, rents, and labor costs, adjusting selling prices is also a necessary measure for businesses to maintain service quality.
In summary, although the reduced Brazilian coffee bean production is indeed a major factor behind this wave of chain coffee price hikes, the real main drivers of the price increases also include container transportation bottlenecks, global inflation, and the overall rise in operational costs. For consumers, understanding these background factors can help them view price adjustments more rationally and also allow for a more directed evaluation of the balance between quality and value when selecting coffee products.
The above content is compiled by CoffeeHunters, a coffee news website.